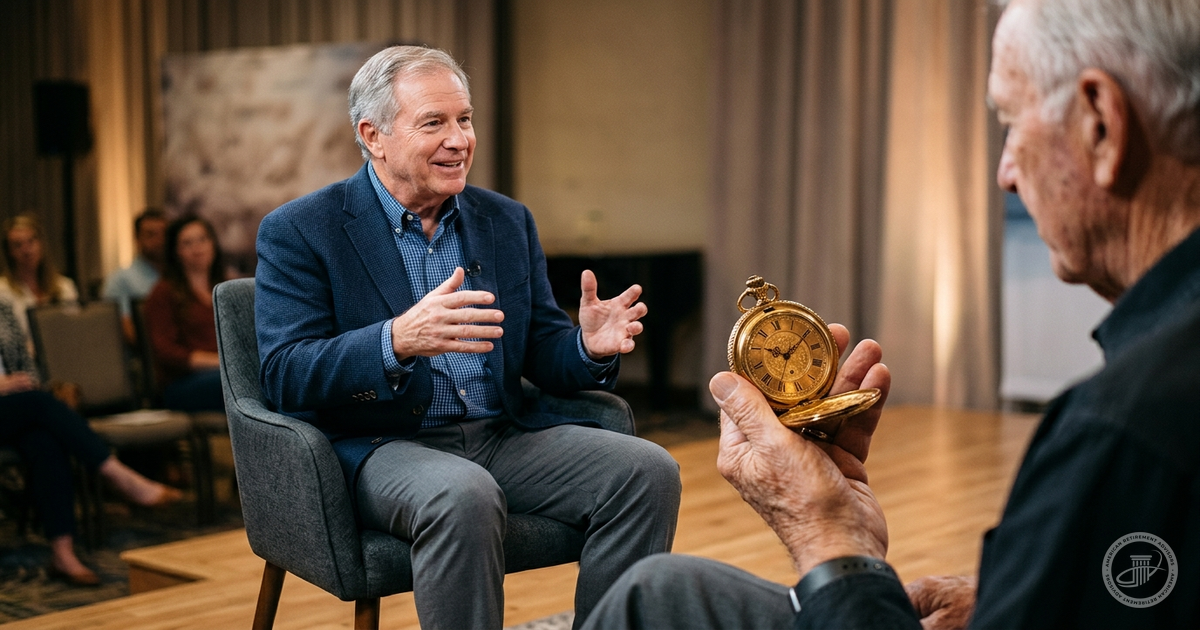
I have spent most of my life around financial advisors, starting at my father's elbow. I love them. And I can tell you, with total affection, that they like to talk. Ask one a simple question and you will get a thorough answer, a little history, a story about a client from 2009, and an invitation to come in and go over the whole picture.
So on Fiscal Fridays, we gave them a clock.
What is the Fiscal Fridays lightning round?
It is the part of the show where David Schaeffer reads a real family's situation off a card and an advisor has thirty seconds to answer it, out loud, in front of the room. The clock is David's 1878 Rockford pocket watch. Run long, and you get the buzzer. Run long enough, and you meet the red spray bottle.
It is not a hypothetical threat. On the September show, Kyle Jacobs ran past thirty seconds, heard the buzzer coming, and pleaded, "Oh my gosh, don't buzzer!" David let him off, because it was a good answer. You can watch that episode on YouTube.
The panel on October 23 is David with Kyle Jacobs and Jason Tweet, and all three have heard most of these questions more times than they can count. The hard part is not knowing the answer. The hard part is saying the one thing that matters before the buzzer does.
Why only thirty seconds?
Because the answer that fits in thirty seconds is usually the one you will remember. A long answer covers everything and leaves you with nothing to act on. A short one has to choose. As our show page puts it, somebody always writes one thing down, and that one thing is the whole point.
The long answers still happen. After the show, the advisors stay in their chairs and take questions from the room. And the show closes with an even shorter round: one question, ten seconds each, David first. But the lightning round is where the one-liners live.
Could we answer in thirty seconds?
We tried. Here are five practice rounds, built from questions families ask every fall and from what we covered on this blog this month. Read aloud at a normal pace, each answer runs about thirty seconds. Start your clock.
"I'm 74 and I write my church a $5,000 check every year. Should I do anything differently?"
Maybe. Starting this year, if you itemize, the first half percent of your income in gifts is not deductible. Since you are past 70½, you can send the gift straight from your IRA to the church instead. It never counts as income, it counts toward your required minimum distribution, and it works whether or not you itemize. Call your IRA custodian before December, and keep the church's receipt. (The full story.)
"My plan has a $0 premium. Why is money coming out of my Social Security for drug coverage?"
That is probably the income surcharge. If your tax return from two years ago showed more than $109,000 single or $218,000 joint, Medicare adds a monthly amount for drug coverage on top of any plan's premium, even a $0 plan, and Social Security takes it from your check. Switching plans will not change it. If your income dropped because of a life change, like retiring, you can ask Social Security to take another look. (The full story.)
"Will my Medigap policy pay for a nursing home if I ever need one?"
Not for long-term care. Medicare's own website says Medicare and Medigap do not pay for it. Medicare covers a short skilled nursing stay after a qualifying hospital stay, mostly for recovery, and after day 100 you pay everything. Long-term care gets paid from savings, from Medicaid if you qualify, or from insurance you buy ahead of time. That is a planning conversation, and the best time to have it is before you need it. (The full story.)
"My plan letter came. Do I have to do anything?"
Read it first. Medicare says that if you have reviewed your options and you are happy with your plan, you do not need to do anything, and your coverage continues automatically. The catch is the word "reviewed." Check that your doctors, your hospital, and your prescriptions still work on the 2027 plan. If they do, relax. If they do not, you have until December 7 to change. (The full story.)
"My Social Security goes up 3.6% in January. How much more will I actually see?"
Probably less than 3.6%. Your Part B premium usually comes out of the check first, and the 2027 premium has not been announced yet. If you pay an income surcharge or have taxes withheld, those come out too. So write down the new gross amount when your notice arrives in late November, then wait for the Part B number before you spend the raise. (The full story.)
Can the advisors beat the clock?
That is the question at Fiscal Fridays, our live educational show. David, Kyle, and Jason will be on the clock on Friday, October 23, at 10:30 AM Arizona time, in our studio in Scottsdale. Doors open at 10:00 for coffee, there are twenty seats, and the panel takes questions from the room after the show. Somebody always writes one thing down. It might as well be you.
Save your seat here, or call (602) 281-3898 and we will hold one for you.
Disclaimer: This article is for educational purposes only. It is not sponsored, endorsed, or otherwise representative of Medicare or the federal Medicare program. American Retirement Advisors is not a government agency. For official Medicare information, visit medicare.gov or call 1-800-MEDICARE (1-800-633-4227).Disclaimer: The information in this article is for educational purposes only and does not constitute tax, legal, or investment advice. Tax laws change frequently, and individual circumstances vary. American Retirement Advisors does not provide tax or legal services. Before making any tax-related decisions, consult a qualified CPA, tax attorney, or financial planner who can evaluate your specific situation.