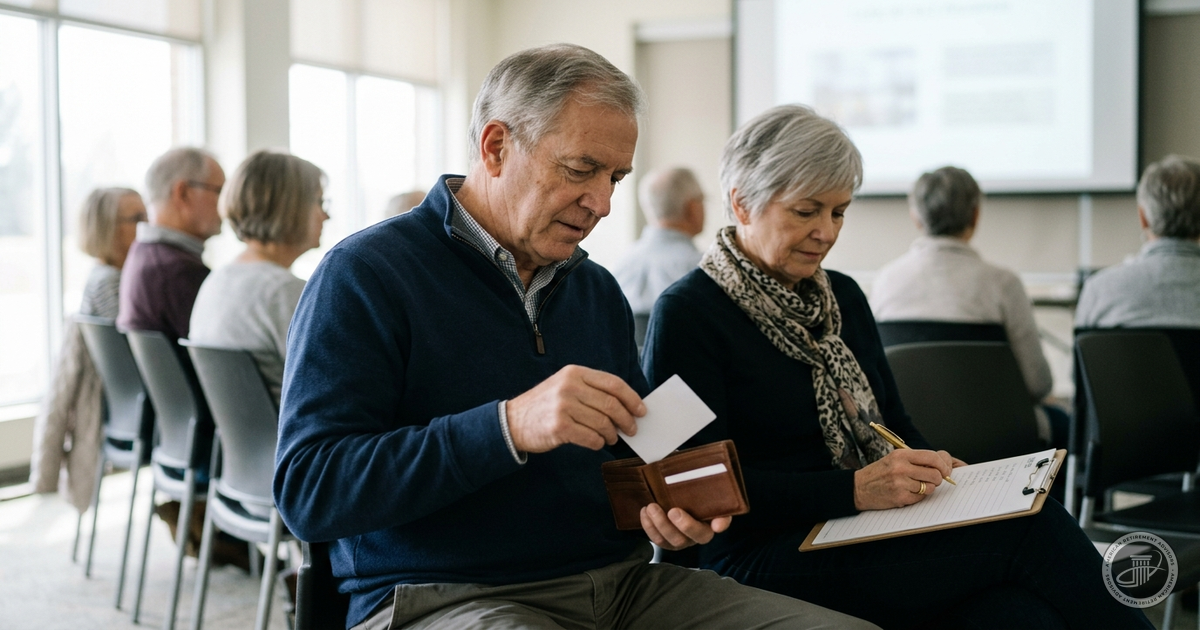
Take-Home Notes, part one. On Friday my father, David Schaeffer, takes the stage at two Phoenix-area libraries with Kyle Jacobs and David Edge for our Medicare workshop, and this week I am putting the whole show in print, one section a day, so you can read ahead or catch up if you cannot make it. I have watched this workshop open the same way for years. Before a single slide about Medicare, the presenters ask the room to take out a wallet or a purse and show that they are covered. As adults in America, we like to be able to prove things on paper. Everybody in that room came for the same peace of mind about their Medicare. So here is the first page of the notes.
What is the foundation everyone starts with?
Original Medicare: Part A and Part B. Medicare.gov labels them in two words each, "Hospital Insurance" and "Medical Insurance", and on Friday's screen they sit side by side on a slab like the foundation of a house. It is a good foundation with one famous crack: after the deductible, Part B pays 80 percent of covered services, and there is no yearly ceiling on the 20 percent that is left for you. Much of the rest of the diagram is about that 20 percent.
What can you build on top of it?
Five ways, and this is the slide the presenters spend the most time on. You can leave the foundation as it is, or put one of four things on top of it. First, employer or retiree coverage, which on the slide hangs off the edge of the foundation on purpose: if you or your spouse still work for an employer with 20 or more employees, the group plan can stay first in line and you can wait on Part B (under 20 employees, the rules flip, which is its own story). Retiree plans may require you to have both Parts A and B. Second, a Medicare Supplement, lettered Plans A to N, which needs Parts A and B and a separate drug plan, because "Medigap plans sold after 2005 don't include prescription drug coverage." Third, a Medicare Advantage plan, which also needs Parts A and B and, in Medicare.gov's words, "Most plans include: Part D." Fourth, Medicaid with an Advantage plan, for people who qualify for both programs.
Which two paths do most people end up on?
Then comes the click the whole section builds to. Employer coverage and Medicaid fade off the screen, and two bars fly in: supplement your Medicare, or assign it to a private plan. Supplementing means Original Medicare stays in charge, a Medicare Supplement picks up much of what it leaves behind, and a stand-alone drug plan covers prescriptions. Assigning means you "join a Medicare-approved plan from a private company that offers an alternative to Original Medicare," and that company handles your Part A and Part B benefits for as long as you are in the plan. Most of the room falls on one side of that fence or the other, and the presenters say it out loud: remember which side you are on, because it decides what changes for you this fall.
Why is my mailbox full of Supplement offers?
Because a lot of companies want the same customer. This is my favorite moment of the show. A list of every company selling Medicare Supplements in the country starts rolling up the screen, and it keeps going for about seventeen seconds. The list we use runs to more than 240 company names, counting each state subsidiary separately. Somewhere around the middle, somebody asks the room, "Anybody getting mail?" and David Edge, playing the client, says he started getting it last week. Then the punchline, straight from Medicare's own booklet on Supplements: "All Medigap plans of the same letter offer the same basic benefits, no matter where you live or which insurance company you buy them from. Price is the only difference between policies with the same letter sold by different companies." Hundreds of names, one set of lettered plans. The envelopes look different. The Plan G inside does not.
Are Advantage plans the same everywhere, too?
No, and that is the second scroll. Advantage plans are not lettered or standardized the way Supplements are. Each one sets its own network, its own copays, and its own extras, so two plans from two companies can look alike on the cover and work very differently at the doctor's office. For one Scottsdale ZIP code, 85255, Medicare.gov's plan search on September 25 listed 17 companies offering 88 Advantage plans for 2026, counting special needs plans. Those are this year's numbers. On October 1, the search switches over to 2027 plans, and Thursday's notes will walk through that search screen by screen.
Can I be on both paths at once?
No. Medicare.gov is plain about it: "You can't buy Medigap while you're in a Medicare Advantage Plan unless you're switching back to Original Medicare," and "You can't use Medigap to pay your Medicare Advantage Plan copayments, deductibles, and premiums." You pick a path. You can change paths later, but the two directions are not equally easy: Advantage plans let you switch every fall with no health questions, while getting back into a Supplement later can mean health questions, which is why the Supplement door can lock behind you.
Your take-home note
Write one line at the top of your notes sheet: I supplement my Medicare, or I assigned my Medicare to a private plan. If you are not on Medicare yet, write not yet, and Friday's notes are for you. Every other section of the workshop hangs on that line. Questions before Friday? The advisors are at 602-281-3898.
Friday, October 2. Foothills Library, Glendale, 10:30 AM. Mustang Library, Scottsdale, 2:30 PM. No cost. Register at 123easymedicare.com/medicare-workshop or call (877) 220-1089.
Tomorrow in Take-Home Notes: the four words the workshop defines before anything else, copay, deductible, network, and maximum out-of-pocket, and the one that surprises people most.
This event is presented by 123EasyMedicare, a brand of American Retirement Advisors, an independent, private organization. It is not sponsored by, endorsed by, or affiliated with Medicare, the Centers for Medicare & Medicaid Services, the Social Security Administration, or any government agency. The libraries are not sponsors of, and are not affiliated with, this event. Educational only; not tax, legal, or insurance advice.
You Finished the Series
Up next: Both Ends of the Table →A seven-part series on the largest wealth transfer in history — for the families on both sides of it.
Disclaimer: This article is for educational purposes only. It is not sponsored, endorsed, or otherwise representative of Medicare or the federal Medicare program. American Retirement Advisors is not a government agency. For official Medicare information, visit medicare.gov or call 1-800-MEDICARE (1-800-633-4227).